Whether a company must have its financial statements independently audited depends on which group it falls into and whether it exceeds the applicable thresholds. Under Article 397 of the Turkish Commercial Code (Law No. 6102), the companies subject to audit are determined by a Presidential Decision. In this article we summarize the groups, the current thresholds, how the three criteria work, and how to answer the question “Is my company subject to audit?”.
İçindekiler
Which Companies Are Subject to Independent Audit?
The Decision divides companies into three main groups:
- Subject to audit regardless of size: companies listed in List (I) of the Decision (for example companies regulated by the CMB, the BRSA, insurance and pension legislation, Borsa Istanbul licensed companies, bonded warehouse operators and EMRA licence holders). Their audit obligation continues without any threshold. Decision No. 11066 also added certain natural gas companies in which state economic enterprises directly or indirectly hold more than 50% of the capital.
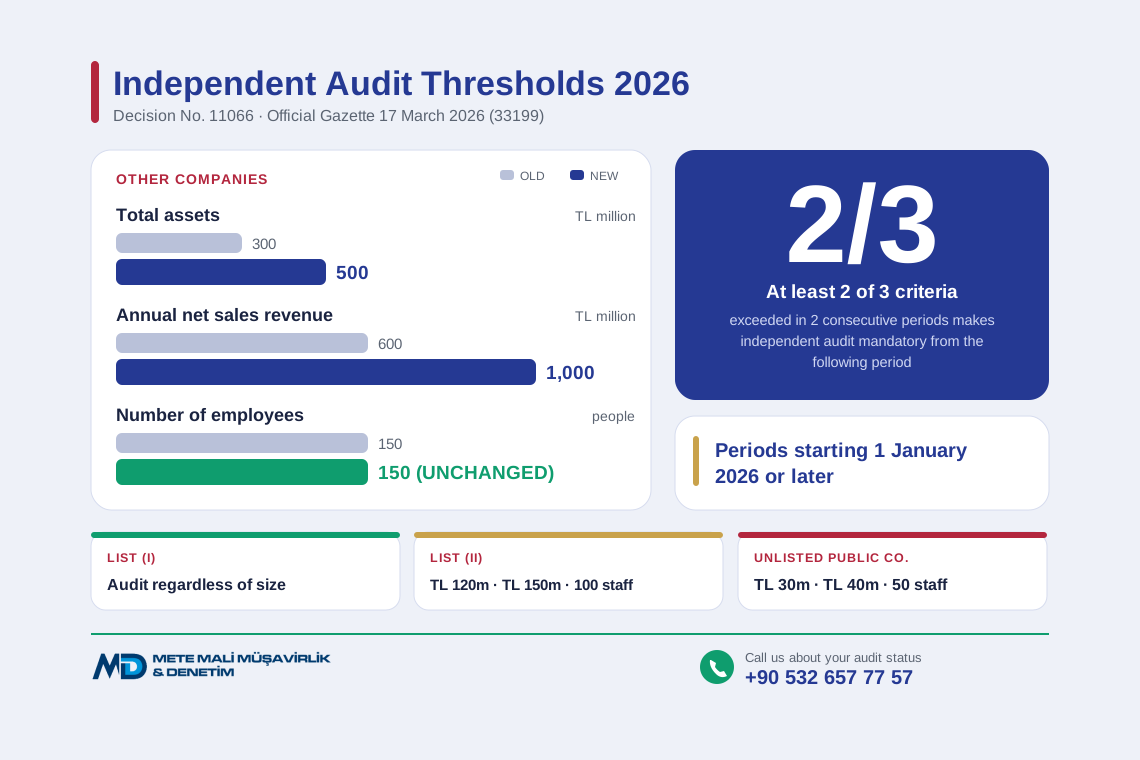
- Companies in List (II): companies regulated by the ICTA, companies managed by the SDIF and companies at least 50% owned by municipalities. Thresholds are unchanged: total assets of TL 120 million, annual net sales revenue of TL 150 million, and 100 employees.
- Other companies: the vast majority of joint-stock, limited and other companies. Their thresholds were raised by Decision No. 11066.
For publicly held companies under the CMB that are not traded on a stock exchange, the thresholds also remain unchanged: total assets of TL 30 million, annual net sales revenue of TL 40 million, and 50 employees.
New Thresholds for Other Companies
For the group that includes most companies, the thresholds changed as follows:
- Total assets: from TL 300 million to TL 500 million
- Annual net sales revenue: from TL 600 million to TL 1 billion
- Number of employees: 150 (unchanged)
Because the thresholds were raised, companies close to the limits should reassess their position.
How Do the Three Criteria Work?
- A company becomes subject to independent audit from the following accounting period if it exceeds at least two of the three criteria in two consecutive accounting periods.
- Total assets and net sales revenue are determined from the financial statements of the last two years; the number of employees is the average of the last two years.
- Companies are assessed together with their subsidiaries and affiliates.
What Should You Do If You Are Subject to Audit?
- The independent auditor or audit firm is elected by the general assembly (Turkish Commercial Code Art. 399). The board of directors then registers the election with the trade registry without delay and announces it in the Trade Registry Gazette and on the company’s website.
- Financial statements and the board’s annual report that are subject to audit but have not been audited are deemed not to have been prepared (Turkish Commercial Code Art. 397). In other words, skipping the audit can invalidate the company’s financial reporting.
- Independent audit is a separate obligation from the tax-oriented certified public accountant (YMM) certification report; one does not replace the other.
Is My Company Subject to Audit? Checklist
- Check whether your company appears in List (I) or List (II) of the Decision.
- Find total assets from the balance sheet and annual net sales revenue from the income statement for the last two years.
- Calculate the average number of employees over the last two years.
- If you have subsidiaries or affiliates, assess them together.
- If you exceed two of the three criteria in two consecutive periods, plan the general assembly process to elect the auditor.
- If you are close to a threshold, assess the likelihood of exceeding it with your CPA in advance.
At Mete CPA & Auditing, we support you from determining whether your company is subject to independent audit to planning the general assembly process. Contact us to review your situation.