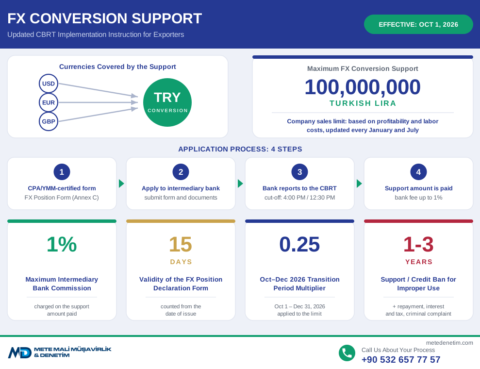
The Central Bank of the Republic of Turkey (CBRT) has renewed its program supporting exporting companies in converting their foreign-currency export proceeds into Turkish Lira. The new “Implementation Instruction Related to the Communiqué on Supporting the Conversion of Companies’ Foreign-Source Foreign Currency into Turkish Lira,” published on September 26, 2026 and effective as of October…
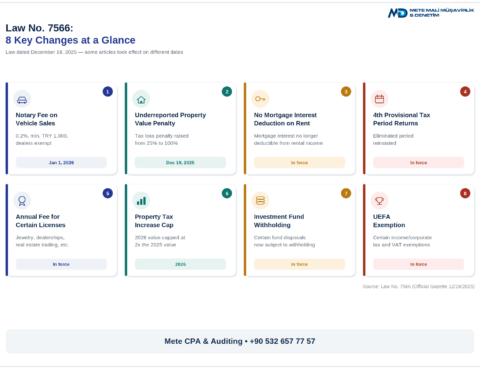
Law No. 7566, published in the Official Gazette on December 19, 2025 and entering into force the same day, introduced wide-ranging changes covering everything from vehicle sales to rental income, title deed transactions, and property tax. Some articles of the law took effect on the publication date, while others entered into force as of January…
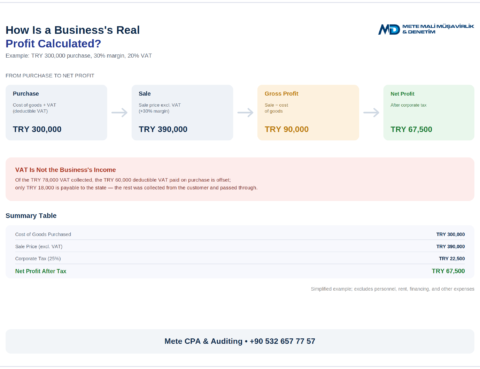
There’s a point business owners frequently confuse: the money that lands in the bank account is not the same as the business’s real profit. The VAT collected on a sale isn’t the business’s own earnings — it’s essentially being held in trust for the state. In this article, we walk through how a business’s real…
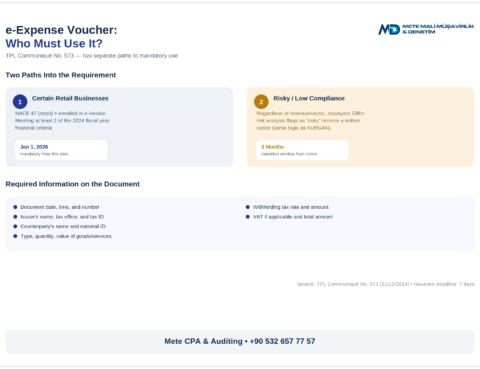
Under General Communiqué No. 573 on the Tax Procedure Law, published in the Official Gazette dated November 12, 2024, the legal groundwork was laid for issuing the “expense voucher” (gider pusulası) electronically, with the Turkish Revenue Administration (GİB) authorized to implement it. Joining e-invoice, e-archive invoice, and e-waybill in Turkey’s e-transformation family, this new document…
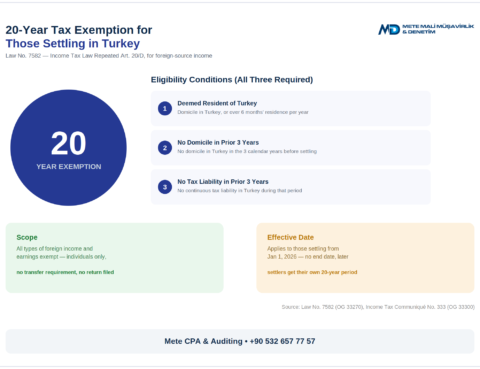
Under Law No. 7582, published in the Official Gazette dated June 4, 2026 (No. 33270), Repeated Article 20/D was added to the Income Tax Law, granting individuals who settle in Turkey a 20-year income tax exemption on their foreign-sourced income. Viewed alongside the Asset Peace regulation we covered earlier, this exemption presents a significant opportunity…
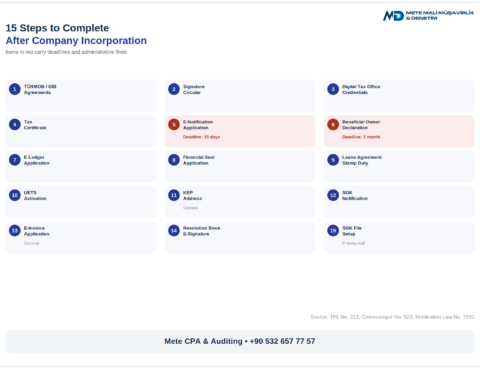
Company formation in Turkey may look complete once the Trade Registry issues the registration, but that’s really just the beginning. Fifteen follow-up steps must be completed afterward — some of them time-sensitive and subject to administrative fines. The minimum capital increase requirement we covered earlier can also apply to this list for existing companies. In…
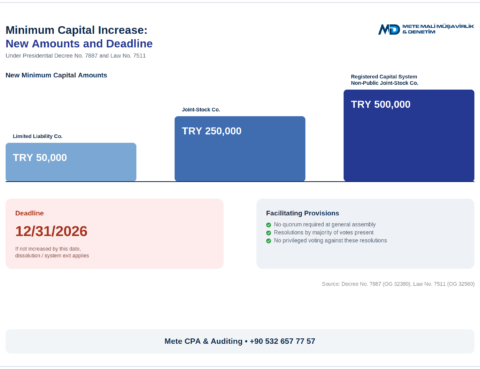
Under Presidential Decree No. 7887, published in the Official Gazette dated November 25, 2023 (No. 32380), the minimum share capital amounts for joint-stock companies (A.Ş.) and limited liability companies (Ltd. Şti.) in Turkey were significantly increased. Subsequently, Law No. 7511, published in the Official Gazette dated May 29, 2024 (No. 32560), granted existing companies a…
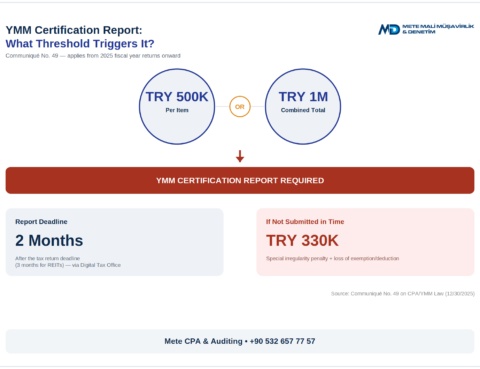
Under General Communiqué No. 49 on the Law of Independent Accountancy, Financial Advisory, and Sworn-in Financial Advisory, published in the Official Gazette dated December 30, 2025 (No. 33123), income and corporate taxpayers must now submit a certification report prepared by a Sworn-in Certified Public Accountant (YMM) in order to benefit from certain exemptions, deductions, and…
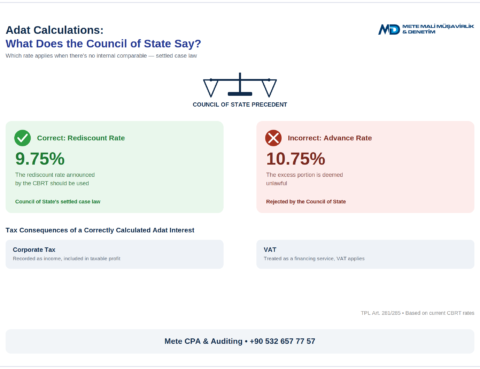
When a company holds cash in excess of its ordinary business needs, or lends money to its partners, one of the most common issues raised in tax audits is which interest rate should be used in the “adat” calculation — the notional interest calculation applied to such balances. Turkey’s Council of State (Danıştay) has established…
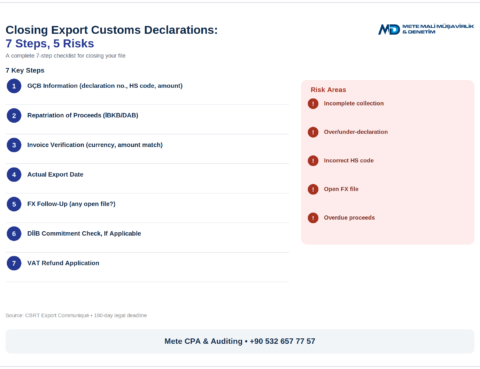
Properly closing the Customs Exit Declaration (Gümrük Çıkış Beyannamesi, “GÇB”) for export transactions is key to avoiding serious consequences such as tax penalties, loss of incentives, and delayed VAT refunds. In this article, we summarize the 7 key steps in the GÇB closing process and the risk areas to watch for. What Is a GÇB…