Receiving the payment for an export is only part of the process. The Export Proceeds Acceptance Certificate (IBKB) issued by your bank documents that the proceeds were repatriated on time and allows the export account to be closed. A portion of the amount tied to the IBKB must also be sold to the Central Bank of the Republic of Türkiye (CBRT). In this article we explain what an IBKB is, how it is issued, the deadlines, the 35% mandatory foreign exchange sale rule, and what can happen if the deadlines are missed.
İçindekiler
What Is an IBKB?
An IBKB (Export Proceeds Acceptance Certificate, İhracat Bedeli Kabul Belgesi) is a document showing that export proceeds have been brought into Türkiye and accepted by the bank as export proceeds. Banks issue it under the CBRT Export Circular.
- The certificate records how the proceeds were brought in, the amount and the date they were credited to the account, together with a note on whether they arrived within the period, within an extension, or after the deadline.
- One IBKB can cover several customs declarations (GBs).
- The IBKB is one of the key documents used to close the export account.
- The Foreign Exchange Purchase Certificate (DAB), issued when the foreign currency is sold to the bank, is used in a similar way; the mandatory sale rate applies to proceeds tied to either an IBKB or a DAB.
How Long Do You Have to Bring the Proceeds into Türkiye?
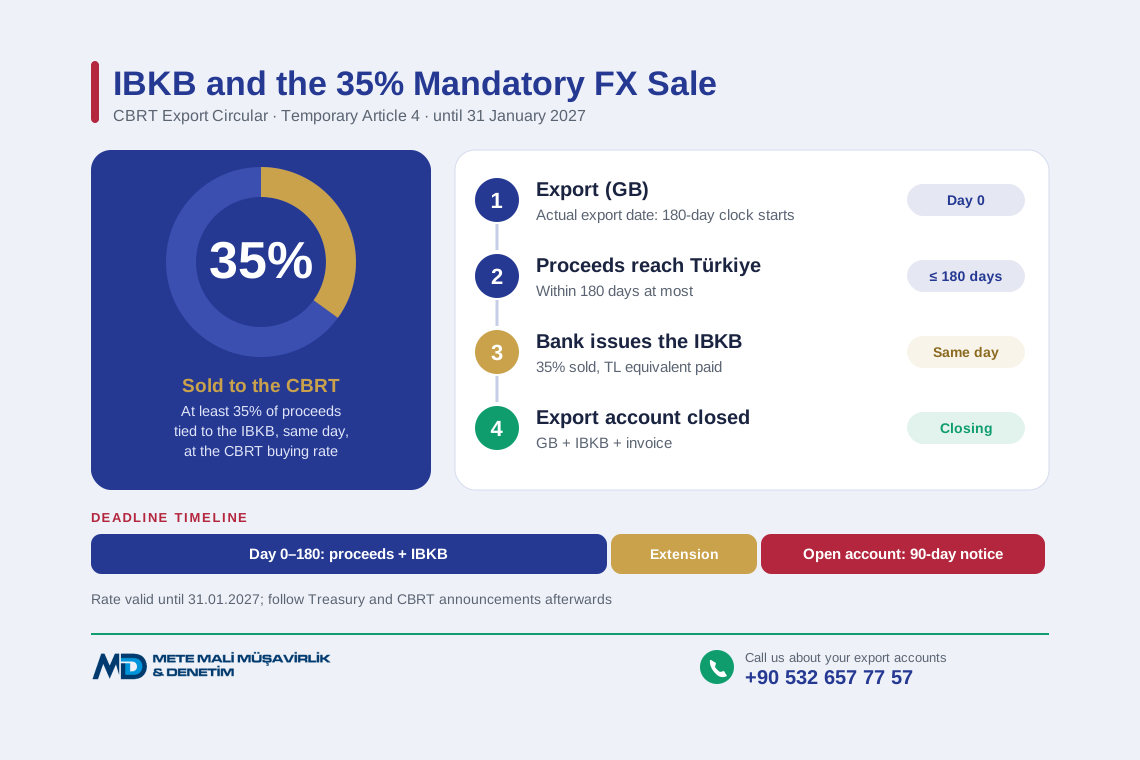
- General rule: at most 180 days from the actual export date. This is a maximum; the principle is that proceeds should be brought in without delay once the importer pays.
- Exports on credit or by lease: proceeds must be brought in within 90 days after the due date set in the contract.
- Consignment exports: proceeds must be brought in within 180 days after the final sale of the goods.
- Extensions: in cases of force majeure or a justified situation, the tax office may grant an extension. For justified situations, extensions can be granted in three-month periods up to six months; longer requests go to the Ministry. The supporting documents depend on the specific case.
The Circular also contains exceptions for certain types of exports and countries. We recommend confirming with your bank and CPA whether your export falls under an exception.
How Is an IBKB Issued?
- 1. The proceeds reach the bank. When the payment arrives, tell your bank which export it relates to (GB number, invoice).
- 2. The bank accepts the proceeds and issues the IBKB. The 35% share of the amount tied to the IBKB is sold to the CBRT on the same day, and the full TL equivalent is paid to the exporter.
- 3. The export account is closed. To close the account, the GB (copy or data), the IBKB, the sales invoice and any set-off or deduction documents are submitted to the bank.
- 4. Where is it closed? The export account is closed at the intermediary bank recorded in box 28 of the GB or at a bank agreed by the exporter.
How Does the 35% Mandatory Foreign Exchange Sale Work?
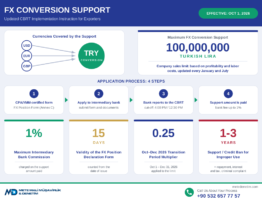
- At least 35% of the export proceeds tied to an IBKB or DAB is sold to the bank that issues the certificate.
- The bank sells this amount to the CBRT on the same day at the foreign exchange buying rate announced by the CBRT for that day. The exporter receives the full equivalent in Turkish lira.
- The rate was 25% from 3 March 2025. It was temporarily raised to 35% from May 2025, and the period has been extended several times. Most recently, Temporary Article 4 extended it until 31 January 2027 (inclusive).
- The base rate in the Circular (Additional Article 3) is 25%. Sources note that if no further change is made after the temporary article expires, this rate applies. It is therefore important to follow Ministry of Treasury and Finance and CBRT announcements toward the end of January 2027.
As a general principle, export proceeds may be freely disposed of (Decision No. 32, Art. 8); the mandatory sale applies to the stated share of the amount tied to an IBKB or DAB.
What Happens If the Deadlines Are Missed?
- If the proceeds are not brought in on time or no IBKB is issued, the export account stays open. The bank reports the open account to the tax office within 5 business days.
- Within 10 business days of the notification, the tax office sends the exporter a 90-day notice.
- If the account is still open at the end of this period and any extensions, the file is reported to the Public Prosecutor’s Office under Law No. 1567 on the Protection of the Value of the Turkish Currency.
Because the scope of sanctions depends on the specific case, we do not give amounts in this article. Businesses with open accounts should work with their CPA without waiting, so that steps such as responding to a notice or applying for an extension are taken on time.
Checklist for Exporters
- Keep a 180-day calendar for every export, starting from the actual export date.
- As soon as the proceeds arrive, send the GB and invoice details to your bank and make sure the IBKB is issued.
- Check the exchange rate applied to the 35% sale and the TL amount paid to you.
- Archive the GB, invoice, IBKB and bank receipts together; these are commonly requested in VAT refund and export exemption reviews.
- Regularly check with your CPA that your export accounts are closed and there is no open-account notification.
- If there is force majeure or a payment dispute, ask about an extension before the deadline expires.
- Follow announcements on the mandatory sale rate toward the end of January 2027.
At Mete CPA & Auditing, we support you from tracking your export proceeds to IBKB and account closing procedures, as well as export-related VAT and tax matters. Contact us to review your situation.